
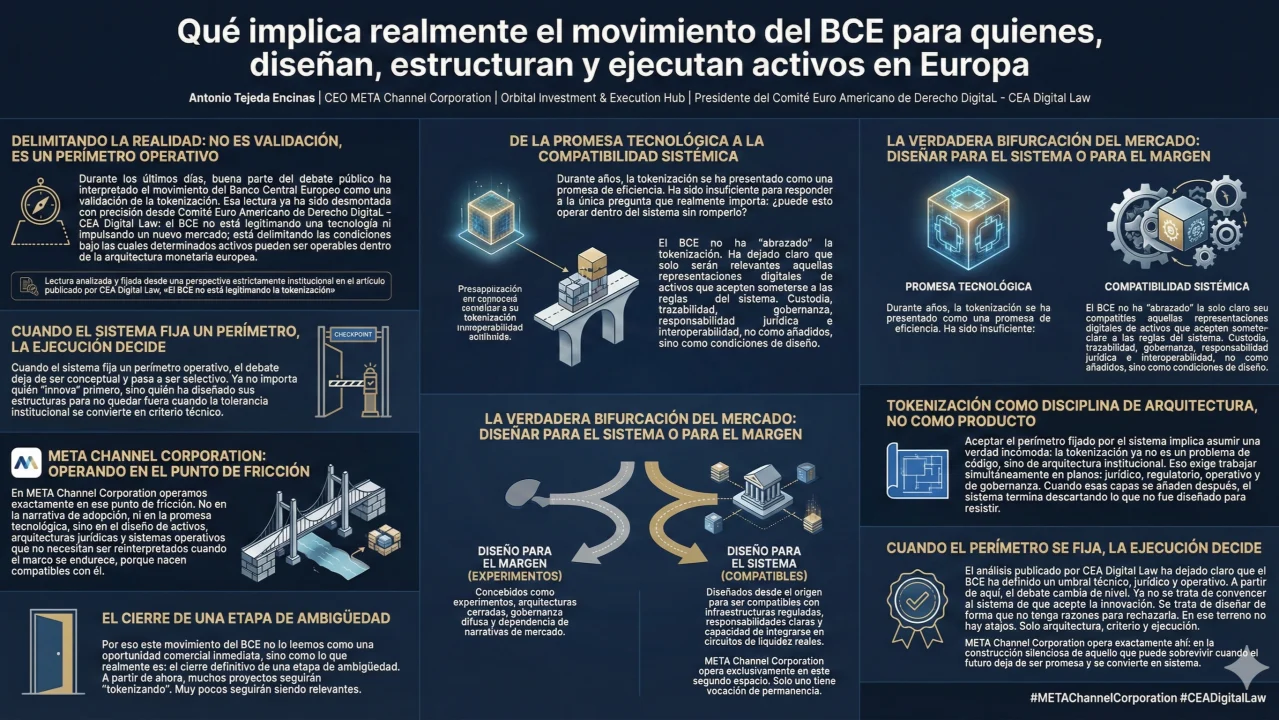
What the ECB’s move really means for those who design, structure and execute assets in Europe
Antonio Tejeda Encinas | CEO META Channel Corporation | Orbital Investment & Execution Hub | President of CEA Digital Law (Euro-American Committee of Digital Law)
Over the past few days, much of the public debate has read the European Central Bank’s move as a validation of tokenisation. That reading has already been precisely dismantled by CEA Digital Law: the ECB is not legitimising a technology or promoting a new market; it is setting the conditions under which certain assets can operate within the European monetary architecture.
This reading has already been analysed and settled from a strictly institutional perspective in the article published by CEA Digital Law, “The ECB is not legitimizing tokenization” (link), which precisely defines the real scope of the ECB’s move. From an execution perspective, that changes the conversation entirely.
When the system establishes an operational perimeter, the debate stops being conceptual and becomes selective. It no longer matters who “innovates” first, but who has designed their structures so as not to be left out when institutional tolerance becomes a technical criterion.
At META Channel Corporation we operate precisely at that point of friction. Not in the adoption narrative or the technological promise, but in the design of assets, legal architectures and operating systems that do not need to be reinterpreted when the framework tightens, because they are compatible with it from the start.
That is why we do not read this ECB move as an immediate commercial opportunity, but as what it really is: the definitive end of a period of ambiguity. From now on, many projects will keep “tokenising”. Very few will remain relevant.
For years, tokenisation has been presented as a promise. A promise of efficiency, disintermediation and wider access to assets traditionally reserved for closed circles. That narrative has been useful for opening conversations, attracting venture capital and justifying technology pilots. It has, however, fallen short of answering the only question that really matters when it comes to scale and continuity: can this operate within the system without breaking it?
The ECB’s recent position, analysed from a doctrinal standpoint by CEA Digital Law, does not introduce a new asset class or legitimise alternative finance models. It sets a clear operational perimeter. A perimeter that definitively separates what can be integrated into the European monetary architecture from what will, by definition, remain outside it. For those operating at the execution level, that perimeter changes everything.
From technological enthusiasm to systemic compatibility
The recurring mistake in the debate on tokenisation has been treating it as an end in itself. There has been talk of blockchain, smart contracts and automation as if technical sophistication were the decisive criterion. It is not. It never has been.
Financial systems do not scale through isolated innovation but through structural compatibility. An asset does not become relevant because it is new, but because it can be held in custody, valued, executed, transferred and, where necessary, absorbed by existing liquidity and risk mechanisms.
The ECB has not “embraced” tokenisation. It has done something far more demanding: it has made it clear that the only digital representations of assets that will be relevant are those that agree to submit to the rules of the system. Custody, traceability, governance, legal liability and interoperability with core infrastructure — not as later add-ons, but as design conditions.
This shift moves the debate’s centre of gravity. The question is no longer whether an asset can be tokenised, but whether it deserves to be designed to survive when the system stops tolerating exceptions. Design for the system or design for the margin This is where the market truly splits.
From now on, two broad families of tokenised assets will coexist. Not because of technology, but because of design intent:
- Those conceived as experiments, with closed architectures, diffuse governance and dependence on market narratives;
- and those designed from the beginning to be compatible with regulated infrastructures, with clear responsibilities and the ability to integrate into real liquidity circuits.
Both can exist. Only one is built to last.
META Channel Corporation operates exclusively in this second space. Not because it is more comfortable, but because it is the only one where execution makes sense in the medium and long term.
Tokenisation as an architectural discipline, not as a product
Accepting the perimeter set by the system means facing an uncomfortable truth: tokenisation is no longer a question of code, but of institutional architecture.
This requires working simultaneously on levels that many projects continue to treat as secondary: legal, regulatory, operational and governance. When those layers are added later, the system ends up discarding what it was not designed to resist.
When the perimeter is set, execution decides
The analysis published by CEA Digital Law has made it clear that the ECB has not legitimised an industry but has defined a threshold. That threshold is not ideological. It is technical, legal and operational.
From here on, the debate moves to a different level. It is no longer about persuading the system to accept innovation. It is about designing in such a way that it has no reason to reject it. There are no shortcuts here. Only architecture, judgement and execution.
META Channel Corporation operates precisely there: not in narratives about the future, but in quietly building what can survive when the future stops being a promise and becomes a system.






